How to buy a house in Rotterdam: a 10-step plan
Follow a clear ten-step plan for buying a house in Rotterdam, from your budget and search to the contract, mortgage and notary transfer.
Process overview
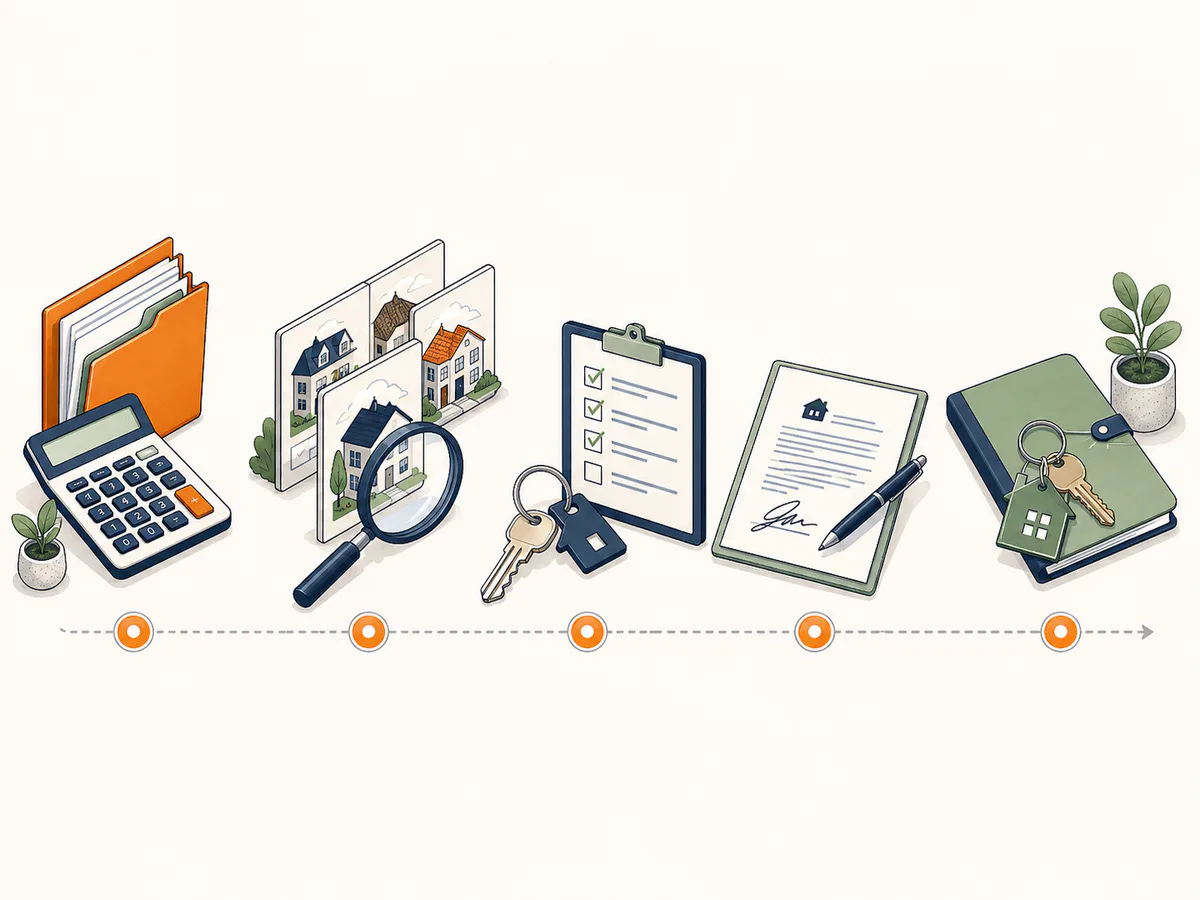
Buying a house in Rotterdam becomes easier to manage when money, search, condition, contract, mortgage and transfer each have a clear place. The ten steps move from a household brief to registered ownership. Some actions overlap after an offer, so use the order as a way to keep responsibility and timing visible.
Estimated time: several weeks to several months, depending on the search, financing and contract.
Preparation: a household budget, property criteria, identity and income records, and access to the professionals responsible for your situation.
End result: a checked purchase with the documents, funds, conditions and handover arranged.
Before you begin
What you’ll need
- a monthly budget and a cash reserve for purchase and moving costs;
- recent income, savings and existing-loan information for a lender or adviser;
- a short list of locations, property types and daily travel needs;
- a viewing checklist for condition, sound, light, storage and outdoor space;
- time to request documents and ask questions before signing.
Important notes
Your lender’s amount and your comfortable housing budget are different questions. Contract conditions, inspection findings, tax treatment, insurance, VvE costs and work after transfer can change the amount you can spend safely. A contract also has legal consequences, so ask the responsible adviser to explain terms that affect your situation.
Quick checklist
- Write down the household’s must-haves and acceptable compromises.
- Separate the lender’s amount from cash needed for other purchase costs.
- Decide which professionals need to review the home or contract.
- Create one folder for offers, documents, questions and dates.
If you have a question about a buying step or document, send your question about the Rotterdam buying process and do not include passports, contracts, bank details or other personal documents.
Step 1: Set your home and location brief
Start with the ordinary week you want the home to support. Record work and school travel, outside space, lift or stair needs, storage, parking, noise tolerance, renovation appetite and the maximum monthly housing cost. Separate firm requirements from preferences that can move.
Choose a small set of areas to test. The Rotterdam city-centre housing context puts street character, daily travel and building fit into the same shortlist question.
Before the purchase sequence starts, living in Rotterdam for home buyers frames city choice around routine, housing type, transport and ownership costs. A brief keeps a lively listing from changing the question halfway through the search.
Check: another person in the household can describe the same priorities without looking at a listing.
Step 2: Set the budget and finance questions
Ask a lender or mortgage adviser how income, debts, interest, property value and personal circumstances affect borrowing. Mortgage borrowing limits depend on income rules and home value, while taxes, advice, moving and other purchase costs still need their own budget.
Before you commit funds, treat Dutch mortgage calculator limits as the boundary between a planning estimate and the lender’s assessment.
The purchase cost categories separate the lender’s amount from taxes, advice, inspection, moving and other cash costs. Add a buffer for inspection findings, small repairs, temporary storage and a change in completion timing. Record which figures are confirmed, estimated or still unknown.
Check: you have a maximum purchase price, a monthly figure you can carry and a separate amount for costs around the purchase.
Step 3: Build a shortlist
Search by the brief, then remove homes that fail a firm requirement before you spend time viewing. Compare floor area, layout, outdoor space, energy information, VvE position, asking price, parking and travel. Keep a short reason for every home that stays on the list.
The official home-buying questions cover mortgage, contract, inspection, transfer and municipal questions, so assign each outstanding question to the responsible party.
Check: the shortlist contains a few homes that meet the same criteria, rather than a collection of attractive exceptions.
Step 4: Visit and inspect the home
Use the first visit to compare the home with its advert and the second visit to test details. Check damp, cracks, windows, roof or façade signals, ventilation, heating, sound, light, storage, shared areas and the condition of appliances that remain. Ask who maintains each shared part of an apartment building.
Walk the street at more than one time of day. Listen for traffic, trams, deliveries, neighbours and construction. Measure the commute door to door and look at the building entrance, bicycle storage and parking arrangement.
Check: your notes separate what you saw, what the seller stated and what still needs professional review.
Step 5: Read the property documents
Request the deed, floor plan, energy information, VvE records and planned works that apply to the home. Look for easements, use restrictions, leasehold or ground-lease terms, service charges, insurance and decisions that may create a future payment.
At the notary transfer, the transfer deed and any mortgage deed are signed, then the ownership change is registered with the Cadastre.
For an apartment, read recent VvE meeting minutes and the reserve position. Ask which work is planned, how it will be funded and whether a special contribution has been discussed. A low monthly service charge can leave more work for later, while a higher charge may include a healthier reserve.
Check: every open document question has an owner and a date for an answer.
Step 6: Make an offer with clear conditions
Set the offer from the checked budget and the home’s condition. Decide which conditions matter, such as financing, inspection, an agreed completion date, included items or a repair arrangement. Put the offer and any conditions in writing through the responsible agent or seller.
Keep emotion separate from the maximum you can carry. A competitive offer can still be a poor fit when a condition is missing or the building documents raise an unresolved issue. Record the expiry time and the next response you expect.
Check: you know what happens if the offer is accepted, declined or answered with a counteroffer.
Step 7: Review the purchase contract
The Dutch purchase contract sets out the property, price, conditions and timing. Ask the responsible adviser to explain any clause you do not understand. Check the names, address, inclusions, completion date, conditions, deposit or bank guarantee, penalties and signatures.
The three-day cooling-off period begins after the buyer receives the signed contract; at least two days must be neither a weekend nor a public holiday. Record when the signed copy arrived. Conditions with a later deadline still need their own diary entry and evidence.
Check: the signed copy is stored, the dates are recorded and the people responsible for each condition are clear.
Step 8: Complete the mortgage and valuation
Send the lender the requested income, identity and property records promptly. The lender may require a valuation or other checks before confirming the mortgage. If the valuation is lower than the purchase price, your cash contribution or the contract conditions may need attention.
Keep your circumstances stable while the application is open and tell the adviser about changes that affect income, debts or employment. Do not assume an initial borrowing estimate is a final approval.
Check: the lender’s approval, conditions and funding date match the completion date in the contract.
Step 9: Arrange the notary transfer
Give the notary the signed contract, lender instructions and identity records requested for the transfer. Review the draft transfer deed and statement of costs. Check how the purchase price, deposit, mortgage funds and adjustments for service charges or taxes will be settled.
The notary appointment completes the handover, so bring the confirmed documents and funds on time. Ask when the final statement must be paid and which documents you should bring.
Check: the appointment, funds, insurance and required documents are confirmed by the notary and lender.
Step 10: Inspect, receive the keys and organise the first records
Visit the home shortly before signing to check that its condition matches the agreement and that included items remain. Record meter readings, keys, remotes, access tags and any agreed repair. Raise a mismatch before the transfer is completed.
After the keys arrive, save the transfer deed, mortgage papers, warranties, manuals, insurance details and VvE contacts in one secure place. Register utilities, arrange the move and note any work that needs a quote or a permit.
Check: you know what was handed over, which follow-up remains and where the records are stored.
Final verification
Before the completion date, check:
- The signed contract and all conditions are stored.
- The cooling-off and condition deadlines are in the calendar.
- The mortgage approval and funds match the completion date.
- The notary has the requested records and identity documents.
- Insurance, utilities, moving and access arrangements are ready.
- The final inspection and handover items are written down.
The purchase is ready for handover when money, documents, dates and responsibility agree across the buyer, lender, seller, agent and notary.
Troubleshooting
The budget is smaller than the shortlist
Return to the brief and decide which feature can move. Compare a different area, floor plan, completion date or level of work. Keep the monthly figure and cash reserve visible while you change the search.
A document is missing
Ask the seller or agent for the exact record, the date it will arrive and the person responsible. Keep the offer or contract condition open until the answer is reviewed by the right adviser.
The valuation is lower than the price
Ask the lender and adviser what the gap means for your cash, conditions and completion date. Recheck the contract before agreeing to a change and keep a written record of the decision.
Tips for success
Do
- Keep one dated decision log for money, documents and questions.
- Visit the street at the times that matter to your household.
- Read shared-building records before treating an apartment as affordable.
- Ask the responsible professional to explain a clause in plain language.
Avoid
- letting a lender estimate become your full spending limit;
- relying on a single visit or a single market comparison;
- signing while a condition or important document is still unclear;
- scheduling the move before the completion date is secure.
A useful habit
After each decision, write the next owner, date and proof needed. This small record makes handoffs easier when several people are working on the same purchase.
Alternative methods
Work with a buyer adviser
When it fits: you have limited time, a complex search or want help with viewings and negotiation.
Benefit: one professional can help keep the shortlist, questions and offer process together.
Trade-off: fees, availability and the adviser’s instructions need to be checked before engagement.
First action: ask what is included, how conflicts are handled and which decisions remain yours.
Search and coordinate yourself
When it fits: you have time to compare homes, request records and manage several deadlines.
Benefit: you keep direct control of the search and the pace.
Trade-off: you carry more responsibility for document review, appointments and follow-up.
First action: set up the same checklist for every home and book expert review when the question exceeds your knowledge.
Time-saving shortcuts
For experienced buyers
- Save a standard document request and update it for each home.
- Use a single comparison sheet for price, area, condition, VvE and travel.
- Group viewings by area and keep a short note immediately after each visit.
Calendar and alert options
- Set alerts for new homes that match the brief.
- Add contract, finance, inspection and notary dates as soon as they appear.
- Use reminders for unanswered document requests and expiring conditions.
Shortcuts save time when they protect the same checks. They should shorten repetition, not remove a decision that matters.
Paperwork check
Before an offer becomes a signed contract, confirm that the address, floor plan, price, included items, VvE position, energy information, conditions and dates refer to the same home. Keep the adviser’s explanation beside the clause it covers.
Before the notary appointment, compare the final statement with the agreed price, deposit, mortgage funds and adjustments. Raise a difference early enough for the responsible party to correct it.
Maintenance and follow-up
After transfer, keep the transfer deed, mortgage papers, warranties, insurance, manuals and VvE information together. Note when building meetings, insurance renewals, planned works and maintenance decisions need attention.
Repeat the document check when a renovation, lease, shared-building decision or change in household circumstances affects the home. A small annual review can prevent an old assumption from guiding a new decision.
Frequently asked questions
How long does buying a house take?
The timing depends on the search, negotiations, mortgage, conditions and notary calendar. A short search can still need several weeks after an offer for documents, financing and transfer. Use dates supplied by the responsible parties rather than assuming a fixed schedule.
What if I make a mistake?
Raise it as soon as you notice it and tell the adviser, lender, agent or notary responsible for that part. Keep the original record and the correction together. Timing matters when the mistake affects a contract condition or completion date.
Can I skip a step?
You can delegate an action, yet the underlying question still needs an owner. A buyer adviser may manage viewings, while the buyer still needs to understand the budget and the offer. A notary can explain the deed, while the buyer still checks the names and address.
Which tools are needed?
A calculator, calendar, document folder and consistent comparison sheet are enough for the organisation. Lenders, inspectors, advisers and notaries add specialist review when the question needs it.
Related processes
Before the purchase sequence
Location fit concerns street character, daily travel and building fit. Budget fit concerns the purchase and ownership costs that must sit beside the price.
After an accepted offer
Keep the contract, mortgage and notary records together. Add every condition deadline to the calendar and ask the responsible person for written confirmation.
A useful comparison
Some buyers need more area detail before they can shortlist; others need a budget conversation first. The right starting point is the question that rules a home in or out.
Quick reference
- Set the home and location brief.
- Set the budget and finance questions.
- Build a shortlist.
- Visit and inspect the home.
- Read the property documents.
- Make an offer with clear conditions.
- Review the purchase contract.
- Complete the mortgage and valuation.
- Arrange the notary transfer.
- Inspect, receive the keys and organise the first records.
Reminders
- Keep dates and document ownership visible.
- Treat estimates as estimates until the responsible party confirms them.
- Ask for help before signing when a term or condition is unclear.
After the ten steps
A good purchase sequence leaves fewer hidden decisions between the first search and the keys. Keep the brief, budget, documents, contract dates and handover record together, and let each professional confirm the part they own.
This ten-step Rotterdam home-buying sequence is general information, not personal legal, mortgage, tax or building advice. Confirm important decisions with the qualified source or professional responsible for your household and property.
Ask us about the Rotterdam buying process